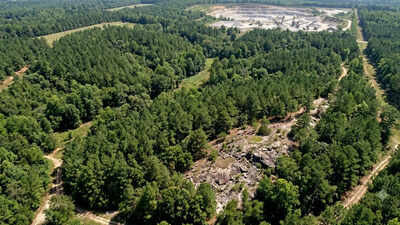
A Georgia landowner claimed a $23 million charitable tax deduction after donating a conservation easement over 103 acres of land. The valuation was based on the argument that the property’s ‘highest and best use’ before the easement was as an aggregate quarry. A US appeals court upheld a much lower valuation of $480,000 and a 40% gross valuation misstatement penalty.The case involves Savannah Shoals, LLC, which donated the conservation easement in 2017 on a 103-acre property in Hart County, Georgia, Reuters reported. On its tax return, the company claimed a $23 million charitable contribution deduction under Section 170 of the Internal Revenue Code.The company’s valuation depended on the proposed quarry use. It argued that the land could be used as an aggregate quarry before the conservation easement was placed on it. The Internal Revenue Service rejected the deduction and also imposed a 40% gross valuation misstatement penalty.Savannah Shoals challenged the IRS decision in the US Tax Court. But the Tax Court agreed with the IRS that the proposed quarry was not the property’s ‘highest and best use’ because it was not a viable use. The court valued the property at $580,000 before the easement and $100,000 after it. The difference resulted in an easement value of $480,000.
Appeals court examined quarry claim
Savannah Shoals then appealed the Tax Court’s decision. The company argued that the Tax Court had used the wrong legal test when deciding the property’s highest and best use.According to the company, the Tax Court had failed to apply a required four-factor test. Instead, it had determined the property’s highest and best use mainly through an analysis of market demand.The 11th Circuit US Court of Appeals rejected that argument. It said there was no requirement in the relevant regulations or case law for the Tax Court to use the four-factor test claimed by Savannah Shoals.
The 103-acre property was placed under a conservation easement in 2017. (Representational AI photo)
The appeals court said the proper framework focuses on whether a proposed use is “reasonably probable, legal, physically possible, and financially feasible.” In this case, the main disagreement was over whether an aggregate quarry would have been financially feasible.That meant the Tax Court was right to examine whether the market could support a quarry on the property. It had concluded that such a use was “highly unlikely”. The appeals court found that the Tax Court’s approach and its reliance on market demand were consistent with the appropriate legal standard.The appeals court also rejected the argument that a proposed use should be considered “financially feasible” simply because it could generate some positive return. It said the analysis had to be based on market realities.
Competition affected property’s value
The Tax Court had also examined the competition that a proposed quarry would face. It found that Savannah Shoals’ experts had overestimated demand for aggregate.At least seven other quarries were located closer to population centres such as Greenville and Athens. According to the Tax Court’s findings, those competitors had significant “delivered price advantages” because they faced lower transportation costs.These competing quarries were an important part of the court’s decision to reject the proposed quarry as the property’s highest and best use. The appeals court found that those findings were enough to support the Tax Court’s conclusion.Once the quarry use was rejected, the Tax Court based its valuation on low-density residential and recreational uses for the property. This resulted in the $480,000 value assigned to the conservation easement.The difference between the claimed deduction and the court’s valuation was substantial. Savannah Shoals had claimed a $23 million charitable contribution deduction, while the Tax Court determined that the easement was worth $480,000.The Tax Court imposed a 40% gross valuation misstatement penalty because the claimed deduction was substantially more than 200% of the correct amount. The 11th Circuit upheld that penalty along with the court’s valuation.