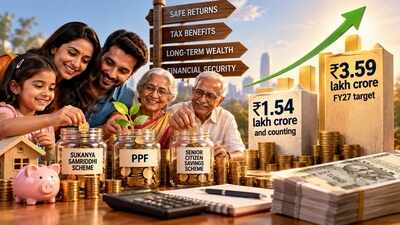
Indians may be moving towards equity investments, but the good old small savings schemes continue to form an important part of their investment portfolio. Be it Public Provident Fund (PPF), Sukanya Samriddhi Yojana (SSY) or Senior Citizens Savings Scheme (SCSS), they are still popular savings options, and fresh data supports this.Interest rates across small savings schemes currently range from 6.9% for one-year deposits to 8.2% for the Senior Citizens’ Savings Scheme and Sukanya Samriddhi Yojana. The Public Provident Fund offers 7.1%, while the National Savings Certificate carries a 7.7% rate, making these schemes more attractive than other savings options. The government-backed security serves as an important pull for Indians looking for safe returns.The net collections under small savings schemes are expected to surpass the budgeted Rs 3.59 lakh crore target for financial year 2026-27 by a comfortable margin, with inflows during the first four months of the fiscal already 56% higher than in the corresponding period last year.Deposits and certificates mobilised through the National Small Savings Fund stood at Rs 1.54 lakh crore between April and July 2026, compared with Rs 98,259 crore during the same period a year earlier. The four-month collection has already reached about 43% of the target set for the entire financial year.
Small Savings schemes popular
Officials expect FY27 collections to come in significantly above the original target, particularly because a substantial share of small savings typically comes in during the March quarter, according to an ET report. The final quarter usually sees stronger demand as taxpayers rush to invest in tax-saving instruments before the financial year closes.Small savings schemes, including the Public Provident Fund, Sukanya Samriddhi Yojana and senior citizen savings schemes, are also providing the central government with an additional source of financing, thereby reducing its dependence on market borrowings.The Centre last week cut its gross market borrowing estimate for the current financial year to Rs 15.99 lakh crore from the Rs 17.2 lakh crore provided for in the Budget. It has also projected Rs 3.87 lakh crore in net financing through small savings during FY27. Net financing from the National Small Savings Fund stood at Rs 1.16 lakh crore during April-July.The current collection trend follows a strong performance in the previous financial year. The government had initially estimated net small savings collections at Rs 3.06 lakh crore for FY26, before raising the estimate to Rs 3.42 lakh crore. Actual collections ultimately exceeded the revised projection by more than Rs 1 lakh crore.For FY27, the government has set the collection target at Rs 3.59 lakh crore, around 5% higher than the revised estimate for the previous financial year.“Despite large retail participation in equity market instruments, the collection trend for small savings is very encouraging and we will comfortably exceed the budget target by a fair margin, almost closer to last year,” a senior official told ET.The official said the strong inflows into small savings indicate that investors continue to seek predictable returns backed by the government, despite the increased participation of larger numbers of investors in equities and other market-linked instruments.
Some popular schemes:
Public Provident Fund (PPF): It has a tenure of 15 years and an investment cap of Rs 1.5 lakh per year. Contributions are eligible for a tax deduction under Section 80C, while the interest earned and the amount received at maturity are tax-free.National Savings Certificate (NSC): The interest is compounded every year and is paid when the certificate matures. The amount initially invested is also eligible for a Section 80C tax deduction.Kisan Vikas Patra (KVP): KVP is built around a simple objective: growing the invested amount to roughly twice its original value over a specified period, depending on the interest rate applicable at the time. It does not provide tax deduction benefits.Senior Citizens Savings Scheme (SCSS): SCSS is specifically meant for senior citizens and retirees. It offers one of the higher interest rates among government-backed savings schemes and provides interest payments at regular intervals. Investments made under the scheme are also eligible for tax benefits under Section 80C. The investment limit is Rs 30 lakh.Sukanya Samriddhi Yojana (SSY): SSY is aimed at building savings for a girl child while offering long-term returns and tax benefits. Parents can make contributions every year, allowing the savings to accumulate over time.(Disclaimer: Recommendations and views on the stock market, or any other asset classes or personal finance management tips given by experts and analysts are their own. These opinions do not represent the views of The Times of India.)