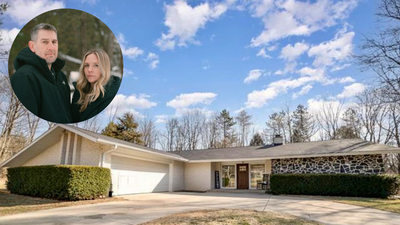
The United States Supreme Court ruled that a Michigan family whose $194,400 home was sold at a public auction over a $2,242 tax debt is entitled to receive only the surplus cash from the sale, not the home’s full open-market value. The judgment in Pung v. Isabella County sets a nationwide legal standard for measuring compensation after a fairly conducted tax sale. Writing for the majority, Justice Samuel Alito said that when local authorities seize and sell a home for unpaid property taxes, “just compensation” under the Fifth Amendment is based on the actual public auction price, not a hypothetical market value. The Court issued its decision on June 23, 2026, vacated the Sixth Circuit’s judgment, and sent the case back for further proceedings.
Dispute over a primary residence tax rate
The legal fight began in Union Township, Isabella County, Michigan. Scott Pung bought the three-bedroom ranch-style home in 1991 for $125,000. The home was the family’s primary residence. After Scott Pung died in 2004, his wife, Donnamarie, continued living there. After Donnamarie died in 2008, their son Marc and his family continued to live in the house. The property remained owned by Scott Pung’s estate, with Donnamarie and Marc as beneficiaries. In 2010, the local tax assessor removed the family’s primary residence exemption. The assessor believed the family had failed to file an updated affidavit showing that the house was still their main home. She therefore taxed it as a second home for tax years 2007 through 2011. The family challenged the decision before the Michigan Tax Tribunal and won. The tribunal ruled that they did not owe the additional taxes charged to second homes. Instead, they owed the ordinary tax rate that applied to a primary residence. Even after that ruling, however, the family faced a real-property tax balance of $2,241.93.
Foreclosure and dramatic resale values
Because of the outstanding $2,241.93 tax bill, Isabella County officials began tax foreclosure proceedings. A Michigan trial court initially blocked the foreclosure, but the Michigan Court of Appeals later allowed it to continue. The county followed the procedures required by the Michigan General Property Tax Act, including a period in which the family could redeem the property, public notice of the sale, and a court judgment of foreclosure. The county then put the ranch home up for public auction. Tax records valued the property at $194,400. Despite that assessment, the highest bidder bought the home for $76,008 at the public tax sale. The investor who bought the home later sold it on the open market for $195,000, nearly the same as its earlier assessed value. The resale happened less than 18 months after the county auction. Meanwhile, Isabella County initially kept all of the auction proceeds.
Lower courts divide over fair compensation
Michael Pung, acting as the personal representative of the estate of Timothy Scott Pung, sued Isabella County in federal court. He argued that keeping the property’s value violated the Takings Clause of the Fifth Amendment and the Excessive Fines Clause of the Eighth Amendment. The federal District Court granted Pung partial summary judgment on his Fifth Amendment claim. The court ruled that the county had to return the surplus from the tax sale. But it rejected Pung’s argument that he should receive compensation based on the home’s full fair market value. Pung appealed to the U.S. Court of Appeals for the Sixth Circuit. The Sixth Circuit affirmed the decision. It ruled that when a municipality sells foreclosed property through a properly conducted public auction, the former owner is entitled to the amount received above the tax debt, and no more. That meant Pung was entitled to $73,766.07, the difference between the $76,008 sale price and the $2,241.93 tax debt.
Supreme Court sets constitutional baseline
Pung asked the U.S. Supreme Court to decide whether compensation should instead be based on the home’s full market value when a tax auction produces a much lower price. The Supreme Court agreed to hear the case and issued its decision on June 23, 2026. The justices held that the auction price is the constitutional starting point for measuring compensation after a tax sale, as long as the sale is fairly conducted in light of the country’s history of tax sales. The Court rejected the idea that the government must pay the property’s hypothetical open-market value. In the opinion, Justice Alito explained that using hypothetical market values could place heavy financial demands on local governments. He wrote: “Pung’s fair-market-value theory would impose unprecedented burdens on jurisdictions that wish to collect unpaid taxes and might well make tax sales impractical.” The Court also pointed to a long history of tax sales in English and American law. It said governments have used property sales to collect unpaid taxes for centuries, while requiring them to return any money left after the tax debt and related costs were paid. The Court concluded that the proper constitutional baseline is the actual tax-sale price, not the home’s hypothetical fair market value. It also ruled that the Eighth Amendment’s Excessive Fines Clause does not require the government to return more than the surplus proceeds from a fairly conducted tax sale.
Concurring opinions highlight auction fairness
Justice Sonia Sotomayor, joined by Justice Neil Gorsuch and Justice Ketanji Brown Jackson, filed a separate opinion agreeing with the Court’s judgment. She stressed that the decision does not define every requirement for a fair tax auction. “I do not read the Court’s opinion as identifying the contours of a fair auction,” Justice Sotomayor wrote. She said the Court was leaving those questions for the lower courts if they were properly preserved in the case. The Supreme Court’s decision vacated the Sixth Circuit’s judgment and sent docket 25-95 back for further proceedings. The family is entitled to the $73,766.07 surplus from the county’s $76,008 public auction, rather than compensation based on the home’s $194,400 assessed value. The Sixth Circuit may also consider arguments about whether the county’s foreclosure and sale procedures were fair, if those arguments were properly preserved.